LPPSA, the public sector home financing board, has raised its maximum home financing to RM1 million. LPPSA’s official rate is a fixed 4% a year, and news reports say the portion above RM750,000 will be charged 4.5% (not yet shown on LPPSA’s portal). LPPSA can finance up to 100% of the property price, over up to 40 years. For civil servants, that brings many RM500,000 to RM1 million homes in the Klang Valley within reach, with less cash upfront. Confirm your own eligibility and start date with LPPSA before you book.
Home financing now up to RM1 million
What changed in LPPSA financing
LPPSA (Lembaga Pembiayaan Perumahan Sektor Awam) finances homes for eligible government employees. In November 2025, LPPSA chief executive Mohd Farid Nawawi announced that the maximum financing would rise from RM750,000 to RM1 million, so civil servants can buy homes that match today’s prices. He also stressed that LPPSA’s 4% rate is fixed and does not change when the OPR rises, and that financing tenure now runs up to 40 years.
EdgeProp reported this month that the RM1 million ceiling takes effect from 4 October 2026, with 4.5% charged on amounts above RM750,000. When I checked LPPSA’s official financing portal on 7 October 2026, its published FAQ still showed the old RM750,000 maximum, so the new terms may not be fully rolled out yet. Please confirm with LPPSA or your HR unit before you commit.
| Item | What we found | Source |
|---|---|---|
| Maximum financing | RM1,000,000 (up from RM750,000) | LPPSA CEO via Bernama |
| Rate up to RM750,000 | 4% a year, fixed, diminishing balance | LPPSA official portal |
| Rate above RM750,000 | 4.5% a year | EdgeProp report (verify with LPPSA) |
| Margin of financing | Up to 100% | LPPSA official portal |
| Maximum tenure | Up to 40 years | LPPSA official portal |
| Effective date of RM1m ceiling | 4 October 2026 (reported) | EdgeProp report (verify with LPPSA) |
Your own offer letter from LPPSA is what counts, so check the rate and amount there before finalising your budget.
Why up to 100% financing matters
A typical bank loan covers about 90% of the price, so on a RM700,000 home you would normally need RM70,000 for the down payment before legal fees and other costs. LPPSA’s ability to finance up to 100% of the price can remove most of that hurdle. For many young civil servants, the down payment, not the monthly instalment, is what stops them buying.
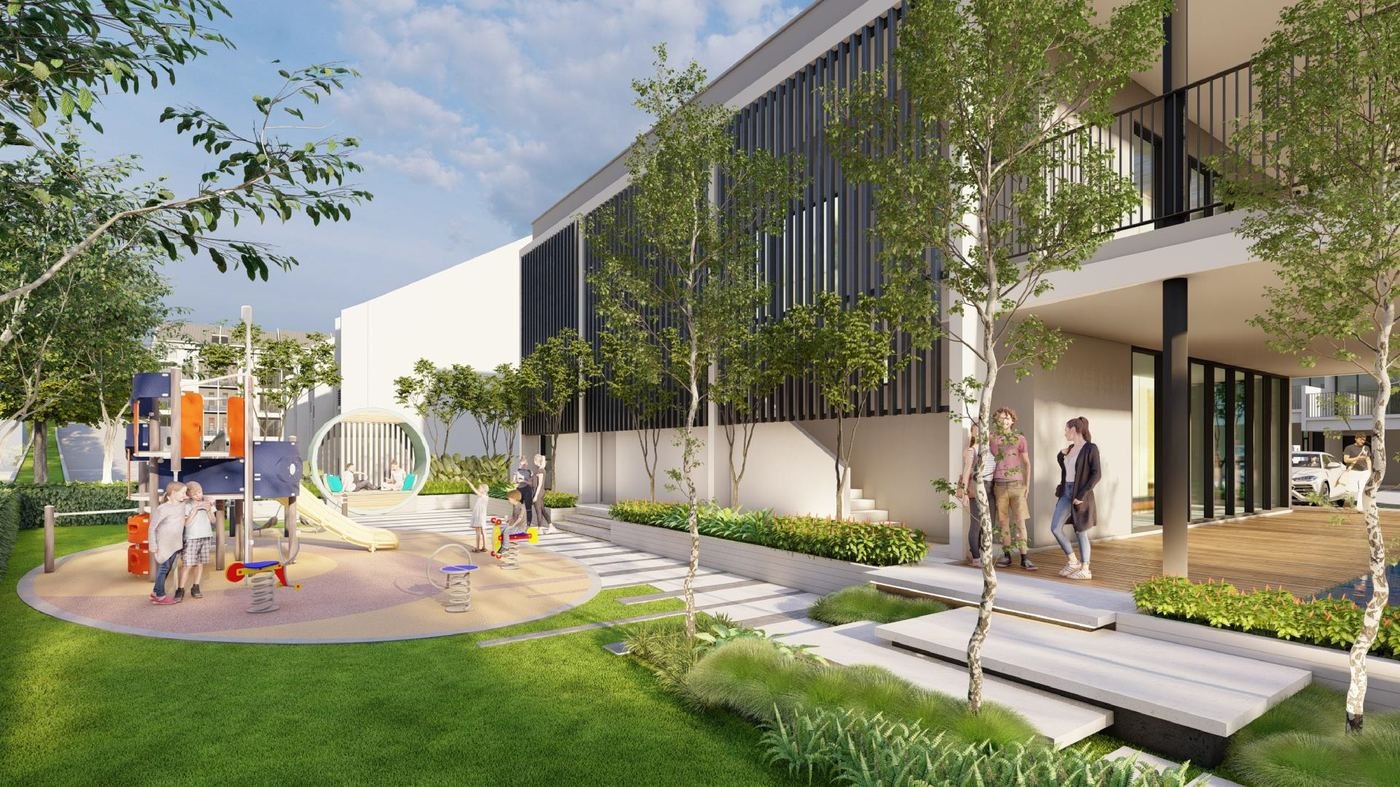
What a RM1 million budget can buy in the Klang Valley
Under the new ceiling, civil servants can look at a much wider part of the market. A few examples from our own research on dms-team.com:
- Freehold townhouse in Cheras South: Residensi Lestari I price list, RM701,500 to RM978,350.
- Completed apartment beside an LRT station: Axis Crown, Ampang, SPA prices from RM449,500 to RM556,600.
- Moving up from an apartment to landed: see what RM700,000 to RM900,000 buys in 2026.
- Budget options under RM500,000: affordable condos near Sungai Buloh and Subang Bestari and our Cheras condo guide.
Not every project or developer works with LPPSA in the same way, so ask before you book whether the developer accepts LPPSA financing and how its payment schedule lines up with LPPSA disbursement.
Bigger loan, bigger commitment: an agent’s checklist
Commentators have welcomed the change but also warned that it only helps if it leads to sustainable purchases rather than simply more household debt. I agree. Before you stretch to the ceiling, go through this list:
- Set your comfortable monthly instalment first, then choose the unit. Use our property loan calculator as a starting point.
- Count the costs beyond the instalment: maintenance fees, sinking fund, insurance, utilities and assessment. Our guide to the real monthly cost of owning a condo shows how these add up.
- Keep a cash buffer. 100% financing reduces the down payment, but you still need money for legal fees, moving and furnishing.
- Check location and resale demand. A larger loan on the wrong home is still the wrong home. Commute, schools and future resale matter more than the size of the loan.
💡 My practical view: the civil servants who do best with LPPSA are the ones who buy below their maximum. Being approved for RM1 million does not mean you should spend RM1 million.
Frequently asked questions
What is the new maximum LPPSA home financing limit?
When does the RM1 million LPPSA ceiling take effect?
Can LPPSA finance 100% of the property price?
Civil servant planning to buy?
WhatsApp DMS Team. We will help you work out a comfortable budget and shortlist homes in the Klang Valley that suit LPPSA financing, free of charge.
About the author: Jason Chan (DMS Jason Chan)
Jason is a registered real estate negotiator (REN 78007) and founder of DMS Team, a property consultancy registered under EUM Realty Sdn Bhd [E(1)1708] with consultants across Kuala Lumpur and Johor Bahru. He researches and reviews every market analysis published on dms-team.com.
This article is general information as at 7 October 2026, written from an agent’s practical perspective. It is not financial or legal advice. LPPSA eligibility, rates and effective dates should be confirmed directly with LPPSA.
Sources: LPPSA official portal: Skim Pembiayaan Perumahan Muda FAQ; Bernama: LPPSA CEO on the RM1 juta limit (Nov 2025); EdgeProp Daily Digest, 2 October 2026; DagangNews: Had pembiayaan LPPSA RM1 juta; FMT: Rehda on the LPPSA RM1 juta limit; Malay Mail: LPPSA raises financing limit to RM1m.
Last updated 7 October 2026 · DMS Jason Chan, REN 78007